Customer Engagement

The Ultimate Refi Customer Journey For 2021-22

5 mins read
September 8, 2021
By
Total Expert

America’s mortgage refi market has 1.98 million more units for lenders now than when 2021 began, but refis still drop very sharply next year. Below, we cover three refi playbooks that enable you to win refi market share and deliver the ultimate refi journey. Let’s start by looking at the market shift that’s coming.

Latest Refi Stats  

In our LinkedIn Live session, we discussed how 2021 has turned out to be a great refi year but 2022 is the opposite. As 2021 has progressed, rates dropped and refi projections rose in reaction to persistent COVID economic risk and removal of FHFA’s adverse market fee.

Current MBA projections call for $1.9 trillion of refi volume this year, which is 19% less than $2.4 trillion last year, but is $790 billion more than the MBA’s January 2021 refi projection.

Now let’s look at refi units to see how many actual refi deals are available to you. Last year’s HMDA data showed 9.18 million refi units closed in 2020. If we divide these refi units by 262,284 licensed loan officers who closed refis last year, that’s 35 refi closings per loan officer.

The MBA predicts 2022 refi units will be down 78% compared to 2020. If true, this would mean there’s only 8 refi closings per loan officer in 2022.

With this in mind, let’s cover three refi playbooks to improve customer journeys and win more market share: (1) speed and precision on rate/term refis, (2) the golden age of debt consolidation, and (3) capturing the home improvement trend.

Playbook 1: Speed & Precision on Rate/Term Refis

Per MBA estimates, there have been about 2.83 million home purchase units funded in America so far in 2021 (January to July), and rates were 0.25% to 0.375% higher in four of these 7 months. To target rate/term refis for these folks, you need 4 things: precision borrower targeting, real-time rate comparisons, early payoff (EPO) risk analysis built in (to avoid fee recapture for refinancing purchase loans closed in the last 180 days), and automated engagement for each individual borrower profile.

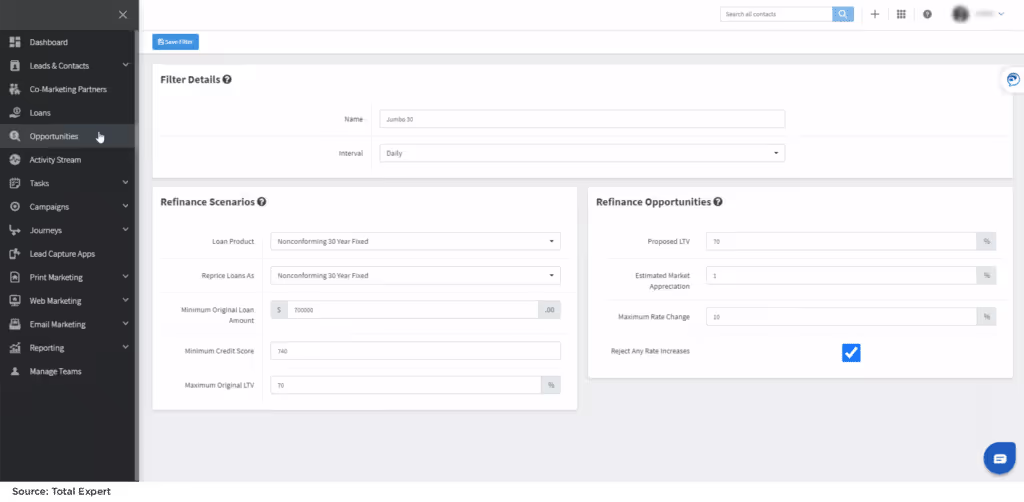
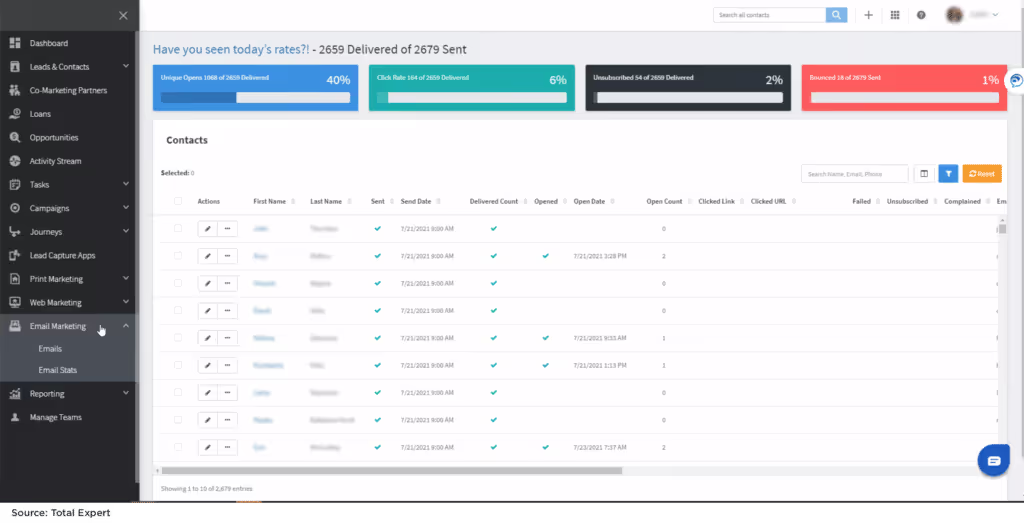
Below is a two-step process showing how Total Expert’s real-time data enables fast action for your salesforce and your customers.

The below shows a Total Expert Opportunities tool that lets sales teams target and filter borrower refi scenarios in real-time. It’s tied into the pricing engine for each loan officer’s pricing so the quotes are precise, and some Total Expert customers configure it to screen out EPOs to control costs.
The second image shows the importance of an automated, personalized customer journey to make your salesforce productive. After your loan officers filter their refi targets, outreach can be automatic based on how you configure. This example shows a refi email campaign deployed, campaign analytics in real time, and customer-level lists so your team can engage with each customer as they interact with campaigns.

This is how you can power your salesforce to develop an entire refi pipeline by pushing a few buttons.
Playbook 2: Golden Age of Responsible Cash Out Refis

We’re now entering a golden age of responsible cash out refis for a few reasons.

First, according to Black Knight, U.S. homeowners now have an all-time record of $8.1 trillion in tappable equity (which means equity that can be taken out before exceeding 80% combined loan-to-value ratio).

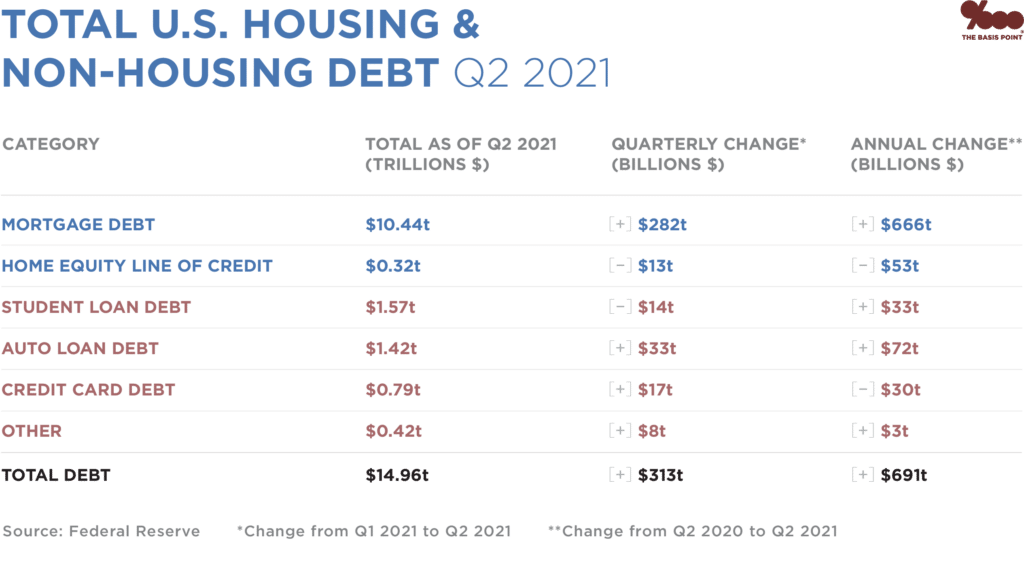
Second, non-housing debt is now double its 2004 levels at $4.19 trillion, as shown in the table below. This student loan, auto loan, credit card, and other debt (personal loans, etc.) mostly has higher rates than mortgage rates. Because of record equity, many borrower profiles can consolidate this debt into a new mortgage without creating loan-to-value ratio risk for themselves or the housing system.
Third, borrower profiles are very strong overall. The below table shows that debt-to-income ratios of recent homebuyers are in the 36 – 37% range, and credit scores of millennials, Gen X, and Baby Boomers are all favorable. In many cases, debt consolidation actually improves these profiles because moving higher rate non-housing debt to housing debt lowers monthly costs, and improves credit scores.

Debt consolidation is truly one of the ultimate customer journeys for 2021-22, and Total Expert powers you to target debt consolidation customers.

Playbook 3: Powering the Home Improvement Trend

Total Expert powers you to engage your customers using their homes, and take immediate action based on how people are engaging with their homes.

People’s emotional connections are with their homes, and according to the Harvard Joint Center for Housing Studies, homeowners will spend $433 billion on home improvement this year.

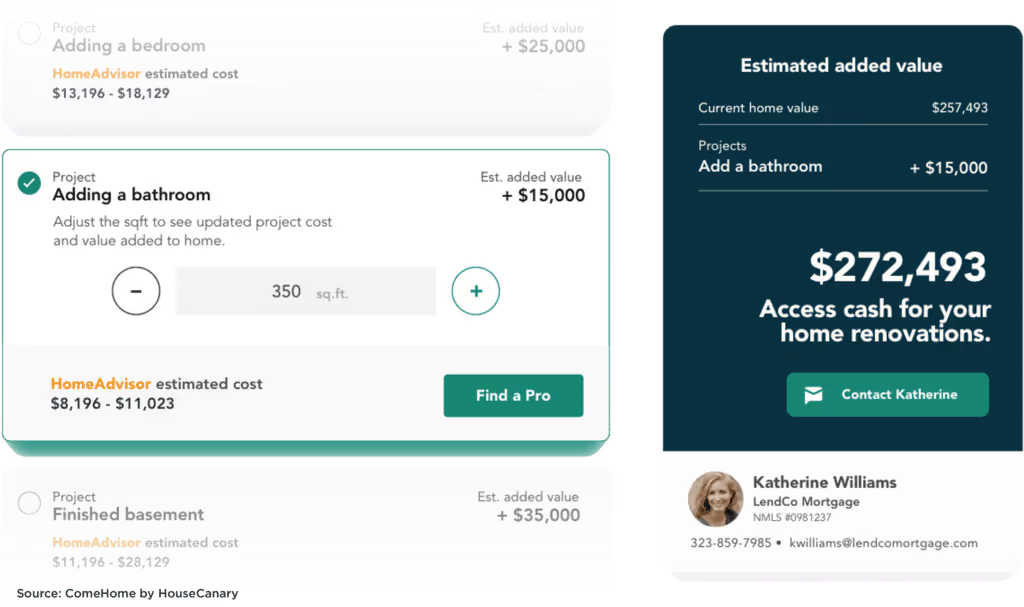
We integrate many valuation/home engagement tools, and the example shows how you can power instant remodel planning, and make loan offers at the same time.

The great part about this is that even if your customer didn’t click on the loan officer contact button when modeling out home improvement ideas, their actions still carry into Total Expert, so you can choose to create automated journeys to follow up on these actions. Or you can create alerts and/or Focused View daily to-do lists for your loan officers to follow up with customers on these actions.
Through these three playbooks, lenders can win refi market share and deliver the ultimate refi journey.
‍

Resources

Related posts

AI

Introducing the 10X Lender Podcast Series

5  mins read
Read more

With the age of superintelligence touching nearly every aspect of our lives, previous limitations to growth are suddenly being removed. In mortgage and lending, we see the opportunity for organizations to create productivity and real business outcomes that are exponential. In the 10X lender series, Total Expert Founder & CEO will sit down with industry leaders to dive into the real-world shifts happening and explore both the natural friction of immense change and the tremendous opportunities emerging. AI superintelligence touches nearly every aspect of our lives, and previous limitations to growth and opportunity are suddenly being removed. In mortgage and lending, we see the opportunity for organizations to increase productivity and create exponential business outcomes.

AI

The 10x Lender: Why AI Demands a New Mortgage Operating Model

5  mins read
Read more

Adding more people to your call center won’t drive the kind of growth you’re seeking. And neither will bolting an out-of-the-box AI onto your existing workflows. That’s the mindset behind becoming a “10x lender,” and the idea that our Founder & CEO Joe Welu unpacked in a recent conversation with HousingWire’s Allison LaForgia.

That shift isn’t incremental. In this new, AI-enabled age, lenders have a real opportunity to do more than simply iterate on processes that have been in place for decades—they can reimagine the entire engine that’s powering their businesses. AI assistants can text, call, schedule meetings, and share information with tens of thousands of borrowers at once. Pair that scalability with the contextual data Total Expert already holds, and your outreach becomes hyper personal, always relevant, and perfectly synchronized with your customer’s financial journey.

For loan officers, that means less time clicking through screens and more time building relationships and educating consumers. This shift isn’t about automating away the work; it’s about elevating your teams’ ability to execute on every possible opportunity.

AI

Why "Faster" Isn't the Goal: Joe Welu on Building Customer-for-Life Lenders with AI

5  mins read
Read more

Most lenders approach AI the way they've approached every technology upgrade for the last two decades: find the part of the process that's slow and make it faster. Total Expert Founder and CEO Joe Welu says that mindset, while understandable, is holding the industry back from the outcomes AI actually makes possible.

In a recent conversation with HousingWire, Joe unpacked the mindset shift he's been sharing with lenders all year: stop optimizing the old process and start reimagining it from a blank canvas.

The problem with doing the same thing “faster"

For years, lending organizations have measured technology's value by a simple test: did it get people to log in and complete a task? New dashboards, new buttons, and new workflows all designed to change human behavior just enough to extract a little more efficiency from the same process.

The catch, Welu explains, is that this approach caps out at the limits of human behavior itself. A loan officer forgets to follow up. A call center rep runs out of time in the day. A relationship goes quiet not because anyone did anything wrong, but because relying on people to be perfect and predictable was never a sustainable strategy to begin with.

What breaks when the old ceiling stays in place

Joe used an analogy at the 2026 HousingWire AI Summit to capture the stakes: a farmer who just got a bigger, faster horse looks to the neighbor’s field and watches them ride by on a tractor. Incremental improvements, like faster horses, were the best option for decades. That's not the case anymore.

The risk isn't hypothetical. We still see lenders asking AI to slightly improve an existing workflow, rather than asking what their workflow should look like with AI built in from the start. And the lenders who are still chasing incremental improvements will find themselves outpaced by competitors who were willing to embrace a new mindset, a new strategy, and new era.  

Joe also highlighted that speed and speed alone will not set you apart. Context will be the critical differentiator in an AI-enabled world. Being the first one to engage a borrower is great, but only if you actually have something to talk about. Historically, a legacy database only knew what a person remembered to type into it. If that information wasn't captured, the system, and the loan officer, wouldn't be able to use it for the next conversation.

Context is king, and the mindset shift that gets you there

This is where Joe took the conversation from diagnosis to direction. Total Expert's Customer IQ continuously aggregates zero-, first-, and third-party data to create a complete financial profile and interaction history for every customer. This provides lending teams with the context they need at the exact moment it matters, whether that's to a loan officer having a conversation or an AI agent handling a task automatically.  

To put things in a perspective that everyone can understand, Joe drew a comparison to how streaming platforms already personalize recommendations based on what the user has watched or listened to previously—i.e., context. When that context is missing, it's obvious and often frustrating. He argues borrowers feel that same disconnect when their lender's outreach doesn't reflect where they actually are in their financial journey.

This level of change doesn't happen without friction. There will be individuals, teams, and even entire organizations that resist this shift. But leaders have to be clear-eyed about the realities of how our industry is evolving and, more importantly, how consumer expectations are driving that evolution.  

The reframe Joe’s pushing lenders toward is to stop measuring success by tasks completed, and start measuring it by the lifetime value of the customer relationship. He calls this “turning relationships into appreciating assets," where organizations never lose a customer and continually find new ways to add value to that relationship over time, rather than treating every interaction as a standalone transaction.

The takeaway

AI doesn't create value on its own. It creates value when it's grounded in real customer context, embedded in the actual workflow, and pointed at a bigger goal than getting a task done faster. For lenders willing to rethink the engine itself, Welu says the payoff isn't incremental. It's the same seismic shift that farmers experienced when they realized that even the slowest tractor was more efficient than the fastest horse.

See Total Expert
in action

Create sustainable growth and increase loyalty with a Customer Operating System that’s purpose-built for financial institutions.
Schedule a demo